Apply the appropriate accounting standards with a clearer implementation plan.
Our IFRS Implementation Dubai service helps UAE businesses assess reporting gaps, document accounting policies, prepare relevant adjustments and organise the information needed for financial statements under the applicable framework.
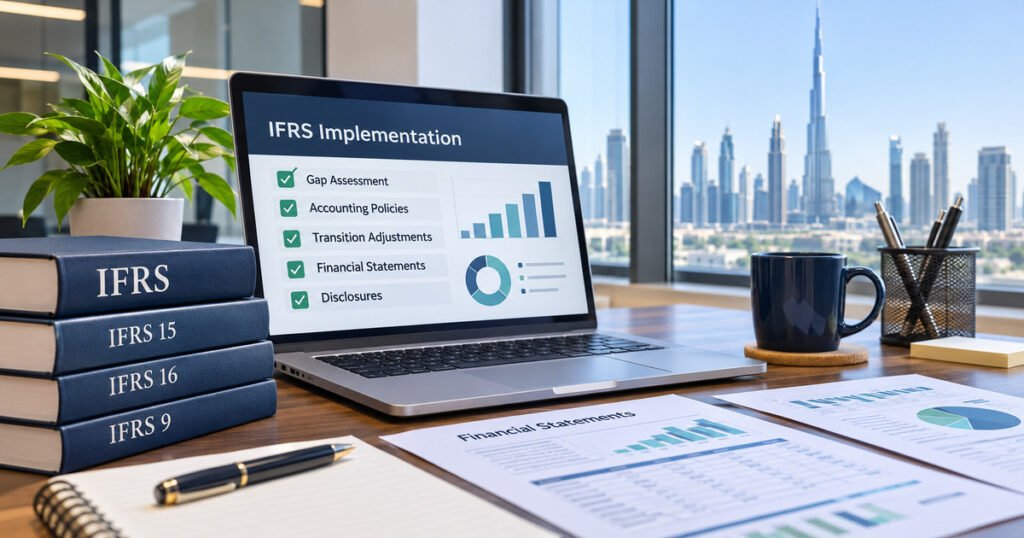
IFRS implementation means applying financial reporting requirements to a company’s actual transactions, balances and accounting processes. It may involve changing the accounting basis, adopting an updated standard, correcting inconsistent practices or preparing reports for a group with specific reporting requirements.
The work is not limited to producing a checklist of standards. It can require decisions about contract terms, measurement methods, supporting calculations, comparative figures and disclosures. Those decisions must be reflected consistently in the records and explained to the people preparing and reviewing the financial statements.
Businesses may seek implementation support when they are:
Not every situation requires a complete conversion project. A company that already applies IFRS may need only a targeted review of one accounting area.
A business should establish its applicable accounting framework before preparing transition entries or revising policies. Full IFRS Accounting Standards and the IFRS for SMEs Accounting Standard are separate frameworks. They differ in some recognition, measurement and disclosure requirements.
For UAE Corporate Tax purposes, Ministerial Decision No. 114 of 2023 specifies IFRS and permits IFRS for SMEs where revenue does not exceed AED 50 million. It also provides for cash-basis accounting in specified circumstances, including revenue not exceeding AED 3 million.
These provisions concern Corporate Tax accounting methods. They do not automatically resolve every company’s legal, regulator, free-zone, group or financing-related reporting obligations. The IFRS Foundation’s IFRS for SMEs guidance also explains the public-accountability restriction on use of that framework.
Framework selection should therefore consider the reporting entity, the users of its statements, relevant external requirements and whether the entity is eligible to apply the chosen standard.
A gap assessment compares existing accounting practice with the requirements of the framework the business needs to apply. It establishes which areas are already supported, which need adjustment and which cannot be assessed until further information is available.
A helpful output is not merely a list of deficiencies. It should explain the potential reporting effect, the information needed, the responsible decision-maker and the proposed order of work. Issues can then be prioritised according to significance and the reporting deadline.
Accounting policies describe how a business applies the selected reporting framework to transactions it actually has. For example, revenue recognition may depend on the obligations in customer contracts, while lease accounting may depend on contract duration, payment terms and relevant options.
IFRS accounting policies in the UAE should be based on the entity’s circumstances rather than copied from another company’s financial statements. Where material judgments are required, the underlying facts, alternatives considered and management’s chosen treatment should be documented.
Depending on the engagement, the output may include policy schedules, technical position papers, proposed calculation methods and a list of matters requiring approval. Management remains responsible for adopting policies and approving significant judgments.
When an entity prepares its first financial statements under full IFRS Accounting Standards, IFRS 1 sets requirements for moving from its previous accounting basis. The process may involve identifying the transition date, preparing an opening IFRS statement of financial position, presenting comparative information and explaining the effects of transition.
Specified exemptions and exceptions can affect the treatment of individual items. They should be considered based on the entity’s actual facts rather than applied automatically.
A transition schedule may compare balances under the previous basis with the amounts required under full IFRS. Each material change should be supported by calculations and an explanation of the accounting treatment. Reconciliations help management and reviewers trace the change from the original records to the revised presentation.
IFRS 1 does not apply to every amendment or policy update. A company already reporting under full IFRS may instead need to follow the transition provisions of the particular new or amended standard.
For businesses applying full IFRS, IFRS 15 can affect when and how revenue from customer contracts is recognised. A review may examine performance obligations, the transaction price, variable consideration and whether revenue is recognised over time or at a point in time.
For example, a business with multi-stage service contracts may need more detail than a company selling goods through simple transactions. An implementation may involve reviewing sample agreements, documenting accounting conclusions and mapping the outcome to invoicing and reporting records.
IFRS 15 concerns the accounting treatment of revenue. Implementing it does not certify that the underlying contracts meet every legal or regulatory requirement.
IFRS 16 may require lessees applying full IFRS to recognise right-of-use assets and lease liabilities, subject to the standard’s relevant requirements and exemptions. The accounting can depend on lease terms, payment schedules, extension or termination options and discount-rate assumptions.
A lease workstream may involve creating a contract register, assessing relevant lease components, preparing initial measurements and identifying entries needed when agreements are modified.
Not every rental arrangement receives the same treatment. The work should examine the actual contracts and reporting framework rather than assume that every payment must be capitalised.
IFRS 9 can affect the classification and measurement of financial assets and liabilities and the assessment of expected credit losses. Relevant balances may include trade receivables, loans and certain other financial instruments.
Implementation may require reviewing available credit information, payment history, contractual terms and the method used to estimate losses. The complexity will vary substantially between an ordinary trading business and an entity with more complicated financing arrangements.
The aim is to establish a supportable approach that can be applied to the relevant records. Estimates must reflect available information and appropriate judgments; using software does not remove those responsibilities.
Some projects also require attention to inventory, fixed assets, impairment, provisions, foreign currency, consolidation or deferred-tax accounting. The applicable requirements depend on the entity’s activities and reporting framework.
A group preparing consolidated statements, for example, may need to review subsidiary reporting packages, intercompany balances and accounting-policy consistency. A business with significant property or equipment may need reliable asset schedules and impairment information.
Specialist valuations, actuarial work and complex insurance-contract implementation should not be assumed to be included. Where needed, those requirements should be separately assessed and supported by appropriately qualified specialists.
IFRS 18, Presentation and Disclosure in Financial Statements, replaces IAS 1 for annual reporting periods beginning on or after 1 January 2027, with early application permitted.
For entities applying full IFRS, the changes include defined subtotals in the statement of profit or loss, requirements concerning management-defined performance measures where applicable, and revised principles for grouping and presenting information.
This is a targeted presentation and disclosure workstream, not a requirement for every business to replace its accounting software. It should also not be confused with the separate IFRS for SMEs framework.
The IFRS for SMEs Accounting Standard was updated in February 2025. The new edition is effective for periods beginning on or after 1 January 2027, with early application permitted.
Relevant updates include changes concerning revenue recognition and other accounting areas. An eligible business currently using IFRS for SMEs may need to compare its existing policies with the new edition, identify affected balances and decide which procedures or disclosures require updating.
Implementation is not complete when journal entries have been drafted. The approved accounting treatments also need to flow through the statement of financial position, profit or loss, cash flows, changes in equity and the relevant notes, as applicable.
A disclosure review can identify missing supporting schedules, inconsistent classifications or information that must be gathered from operational teams. It can also distinguish disclosures supported by existing records from those requiring further estimates or management explanations.
This is different from recurring financial reporting services. Implementation establishes or changes the reporting approach; ongoing reporting applies that approach when preparing future statements.
An IFRS implementation can reveal weaknesses in the chart of accounts, contract registers, reporting fields or supporting spreadsheets. Those gaps may make it difficult to reproduce calculations or prepare consistent disclosures even when the accounting policy itself is appropriate.
Some requirements can be addressed with revised schedules, templates and review controls. Others may require agreed configuration changes or improved data capture. If the work involves software selection, major configuration or migration, it should be considered under a separate accounting system implementation scope.
Technology can support accurate recordkeeping, but it cannot independently approve accounting judgments or guarantee ongoing compliance.
Our IFRS Implementation Dubai approach uses the following stages, adjusted to the reporting requirements and agreed scope.
Identify the reporting entity, the selected framework, affected periods, deadlines and main issues. Agree the intended deliverables and any work outside the engagement.
Examine the relevant financial records, policies and contracts. Record missing evidence and determine whether specialist inputs or management decisions are needed.
Prepare a gap assessment showing material differences, proposed actions and dependencies. Focus the work on areas that affect the actual reporting requirement.
Prepare the agreed technical analysis, policy recommendations, calculations and adjustments. Confirm the assumptions and decisions requiring management approval.
Map approved treatments to the reporting records, financial statements and disclosures. Identify any control or data changes needed to maintain the approach.
Discuss outstanding items, explain deliverables and agree any separately scoped follow-up support. Standalone IFRS training is available as a distinct service rather than an automatic part of implementation.
The precise request depends on the project. Useful documents may include:
If older accounting periods are incomplete, backlog accounting may need to be addressed before reliable transition figures can be prepared. Sensitive records should be requested through a suitable agreed process, not through a basic website enquiry form.
Depending on the agreed scope, a project may produce:
These are possible outputs, not a promise that every engagement includes every document. The deliverables and review responsibilities should be defined before work begins.
Management is responsible for maintaining records, approving significant estimates and policies, and preparing its financial statements. An implementation adviser can assess issues and prepare agreed supporting work, but cannot transfer those responsibilities away from the entity.
An external auditor may review management’s accounting treatments when performing an independent audit. Implementation work does not provide an audit opinion or guarantee that a particular auditor will agree with every judgment. Coordination and requests for additional evidence should be handled within the agreed scope, with independence requirements considered where relevant.
There is no reliable standard price or completion period for all IFRS implementations. A focused change to financial statement presentation differs from a first-time adoption covering several entities and comparative periods.
Important factors include the number of reporting entities, complexity of transactions, quality of historical records, required technical analysis, data availability, reporting deadlines and need for specialist input. A useful proposal should identify deliverables, assumptions, management responsibilities and any work that would need separate approval.
IFRS implementation changes or establishes accounting treatments and the supporting reporting process. It should not be confused with:
For tax-specific questions arising from accounting changes, Corporate Tax advisory services may be relevant as a separate assignment. No accounting implementation can guarantee a particular tax assessment, regulatory outcome or external audit conclusion.
A useful implementation plan makes the accounting issues, source information and decisions visible. It helps management distinguish necessary work from optional systems changes and understand what the final schedules and policies will be used for.
Our approach is to begin with the reporting purpose, identify the relevant gaps and describe deliverables in practical terms. Claims about specialist capabilities or past project outcomes should be supported by evidence rather than assumed from the service name.
If you need IFRS Implementation Dubai support, share the reporting framework you currently use, the financial period involved and the issue prompting the project. An initial discussion can help identify the information needed, likely workstreams and appropriate next steps.
Let our experts manage your books while you grow your business.
We’re always on the same page with Government Agencies, working together to get the job done!
Posted on Google
 kamil khan
Trustindex verifies that the original source of the review is Google.
My Experience of taking Accounting & Taxation services from Virtual Accountants (VA) was phenomenal. I would Reckon VA as best for Accounting & Tax services to SME'sPosted on Google Liubov ShchurkovaI’ve been working with Virtual Accountants for several years now, and they have consistently delivered the level of support and professionalism I expect. Their team is always highly responsive and prompt in communication, which makes the entire experience smooth and stress-free. What I particularly appreciate is their attention to detail — every question I’ve had has been answered thoroughly and clearly. All reports are prepared with precision and always delivered on time, without the need for reminders or follow-ups. Their reliability and expertise have made them a trusted partner in managing our company accounting needs. I can confidently recommend Virtual Accountants to anyone looking for accurate, timely, and dependable financial support.Posted on Google
 Thea DivinoWe appreciate your proactive communication and quick turnaround. It makes our job easier.Posted on Google
 Elin StensdotterWorking with Virtual Accountants continues to be a great experience. They are organised, reliable, and consistently proactive. Exactly what we need and look for in a financial partner. Their structured and forward-thinking approach allows us to stay focused on our core business, knowing they have everything else under control. It's incredibly reassuring to work with a team that not only keeps things in order but also anticipates our needs before we even raise them. We highly recommend Virtual Accountants to any company looking for a professional and dependable accounting partner.Posted on Google
 Info IskillWe’ve been working with this accounting company for over 3 years. Always professional, reliable, and a pleasure to deal with. They provide clear advice, work with integrity, and offer great value for money. Highly recommended!Posted on Google
 Kalle NeumannDear fellow company owners in UAE. I've been running my own company for 40 years, and I've had many accountants all over the world, but I can tell You that Umar Abdullah and his team at Virtual Accountants is one of the most dedicated and professional accountants I ever have experienced. Thank You Umar & Team!!!Posted on Google
 Farooq ButtMy accountant left and I was worried. Then I found Virtual Accountants and they made my life easy. Very happy with their team, highly recomended.Posted on Google
 Muhammad UmairVery good services, I am impressed by Mr. Sajid and his team.Posted on Google
 CA Sohel ShaikhI highly recommend Virtual Accountants LLC for their outstanding accounting and bookkeeping services in Dubai. Their team is highly professional, detail-oriented, and incredibly responsive. They have helped streamline our financial processes, ensuring accuracy and compliance with UAE regulations. What sets them apart is their dedication to client satisfaction—they provide timely reports, offer valuable financial insights, and are always available to address queries. Their expertise in VAT, payroll, and corporate tax has been invaluable to our business.Verified by TrustindexTrustindex verified badge is the Universal Symbol of Trust. Only the greatest companies can get the verified badge who has a review score above 4.5, based on customer reviews over the past 12 months. Read more
IFRS implementation involves applying the relevant accounting framework to an entity’s transactions, policies, balances and financial statements. It may include a gap assessment, accounting adjustments, supporting schedules, disclosures and a handover to the finance team. The work depends on the reporting objective.
Businesses may need help when adopting full IFRS for the first time, responding to a new standard, meeting group-reporting requirements or addressing material accounting differences. A single technical issue may require a focused engagement rather than a complete conversion.
Not necessarily. The applicable framework depends on the entity and reporting purpose. UAE Corporate Tax rules permit IFRS for SMEs where the relevant revenue threshold is met, while other legal, regulatory, group or financing obligations may impose additional requirements.
It compares current accounting practices and records with the selected reporting framework. The findings may identify required changes, missing supporting information, significant judgments and priorities for implementation. The output should help define the scope rather than merely list standards.
No. IFRS 1 addresses first-time adoption of full IFRS Accounting Standards. An entity already reporting under full IFRS generally follows the relevant requirements for the particular new or amended standard instead. The reporting history must be reviewed before choosing a transition approach.
Yes. A business may need to implement an amended standard, improve policy documentation, review specific calculations or change its financial statement presentation. The engagement should focus on the identified need rather than repeat the entire framework adoption process.
Initial information may include recent financial statements, trial balances, accounting policies, contracts, asset schedules and group-reporting instructions. A detailed document request should be based on the agreed scope. Material missing records may delay certain calculations.
No. Those standards are assessed where they are relevant to the entity and the reporting framework. A business with complex customer contracts, leases or financial instruments may need targeted work, while unrelated standards should not be added simply to increase the project scope.
IFRS 18 becomes effective for annual periods beginning on or after 1 January 2027, with early application permitted. It replaces IAS 1 and changes aspects of presentation and disclosure, including defined profit-or-loss subtotals. The impact depends on the entity’s reporting structure.
It may be if your entity is eligible for and uses IFRS for SMEs. The updated edition takes effect for periods beginning on or after 1 January 2027, with early application permitted. Its requirements should be assessed separately from changes to full IFRS.
Not automatically. Some changes can be implemented through accounting-policy updates, revised schedules and reporting templates. Where software cannot capture the necessary information, configuration or migration may need separate assessment and approval.
The timeframe depends on reporting periods, number of entities, technical complexity, records available and management decisions. A realistic schedule can be proposed after the main issues and dependencies have been reviewed. No single duration applies to every engagement.
Fees depend on the scope, entities involved, number of accounting issues, record quality, required schedules and any specialist input. A proposal should identify the agreed deliverables and distinguish them from additional work that would require separate approval.
Management retains responsibility for the financial statements and significant accounting decisions. Implementation support may provide analysis, calculations and recommendations, but approval and continuing recordkeeping responsibilities remain with the business.
Not automatically. IFRS implementation concerns accounting and reporting changes. An independent audit, legal advice, Corporate Tax interpretation or return filing requires separately agreed work and an appropriately authorised provider where applicable. Implementation does not guarantee auditor or tax-authority acceptance.
Office 609, 6th Floor, Al Moosa Tower 1, Trade Centre 1, Sheikh Zayed Road, Dubai, UAE
Sharjah Media City (Shams), Al Messaned, Al Bataeh, Sharjah, United Arab Emirates.