Maintain accurate financial records, reconcile gold inventory and prepare reliable reporting with accounting support designed for gold and precious-metals businesses.
Virtual Accountants LLC provides gold trading accounting services in Dubai for bullion dealers, jewellers and precious-metals and stones traders. Our support covers bookkeeping, stock and bank reconciliation, management reporting, VAT-ready records, Corporate Tax accounting support and year-end preparation.
Gold trading creates accounting challenges that go beyond ordinary transaction recording. Quantity, weight, purity, inventory movements, pricing, settlement and supporting documentation all need to connect correctly with the accounting ledger.
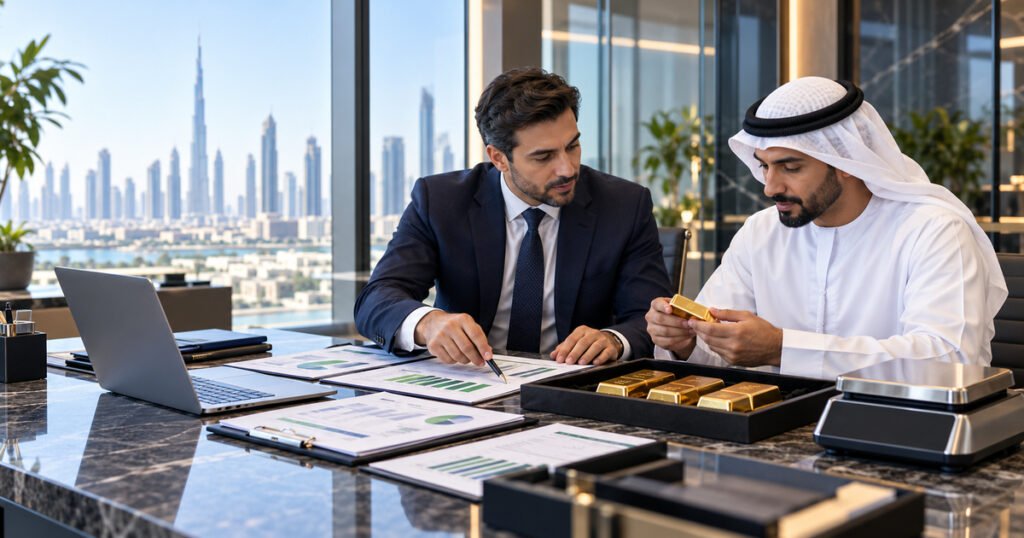
A gold trading company’s accounts should provide a clear financial trail from the purchase or receipt of stock through to its sale, transfer or other movement.
That becomes more difficult when a business handles high transaction values, different weights and purities, multiple suppliers and customers, foreign currencies, physical stock and frequent price movements.
Reliable gold trading accounting brings these records together.
The objective is to maintain financial information that allows management to understand stock, margins, receivables, payables and cash while also supporting VAT records, Corporate Tax preparation and year-end financial reporting.
Our scope is tailored to the company’s actual trading model, transaction volume, accounting system and condition of its existing records.
Gold held for trading can form part of a company’s inventory, but managing that inventory requires information that a conventional stock ledger may not capture adequately.
The accounting records may need to connect:
Weak reconciliation between these records can distort inventory values and gross margins and create additional work during month-end reporting or the external audit.
For this reason, gold inventory accounting should combine financial records with disciplined stock-control and reconciliation procedures.
The accounting scope depends on how the company trades, stores and settles gold and other precious metals.
Day-to-day bookkeeping establishes the financial record behind the trading activity.
This may include recording purchases and sales, expenses, receipts, payments, supplier balances, customer balances and other transactions relevant to the business.
Posting rules should be applied consistently so that gold trading activity can be analysed alongside the company’s wider financial position.
Where the existing books contain incomplete or inconsistent historical records, additional accounting cleanup may be required before an ongoing monthly process can be established.
Inventory is one of the most important accounting areas for a gold trading company.
Stock records should be capable of supporting the quantities and values recorded in the accounts.
Depending on the trading model and available data, the accounting process can include reconciliation of:
Weight and purity information should also be maintained where relevant to the company’s products and inventory system.
Inventory differences should be investigated rather than simply adjusted without explanation. A clear variance record helps management understand why physical stock and accounting records differ.
Gold purchases and sales should be recorded in a way that allows the underlying commercial transaction to be traced to the accounting entry.
Relevant records can include supplier invoices, customer invoices, settlement information, inventory movements and payment documentation.
Where the company trades in different product forms or categories, the accounting structure should provide enough detail to understand revenue, cost of sales and margins without making the chart of accounts unnecessarily complicated.
Bank records should reconcile with the transactions recorded in the accounting system.
For gold traders with high-value or frequent settlements, unresolved differences can quickly make customer, supplier and cash positions difficult to understand.
Regular accounts reconciliation helps identify missing transactions, duplicated entries, unmatched receipts, outstanding payments and other differences before they accumulate.
Gold trading companies may purchase or sell in AED, USD or other currencies.
Where multiple currencies are used, the accounting system should record transactions using an appropriate exchange rate and account for relevant foreign-exchange differences in accordance with the applicable accounting framework.
Bank and supplier/customer balances should also remain reconcilable to the underlying records.
The precise accounting treatment depends on the transaction and the company’s reporting framework.
Periodic management reporting should help management understand more than total revenue and expenses.
Depending on the available accounting and inventory data, reports may include:
The purpose is to turn the accounting records into financial reporting that management can actually use.
Gold inventory should not automatically be assigned one accounting treatment simply because the underlying commodity has an observable market price.
Under IAS 2 Inventories, inventories are generally measured at the lower of cost and net realisable value.
The cost of inventory can include purchase costs and other costs incurred in bringing the inventory to its present location and condition, subject to the requirements of the applicable accounting standard.
IAS 2 contains a specific measurement exception for qualifying commodity broker-traders.
Where an entity meets the relevant definition and holds qualifying inventory within that scope, the inventory is measured at fair value less costs to sell, with changes recognised in profit or loss.
This treatment should not be applied automatically to every gold trading business.
Whether the exception applies depends on the nature of the business and the circumstances in which the inventory is held.
Whichever accounting treatment applies, the company needs records capable of supporting the inventory amounts reported in its financial statements.
That may require consistency between:
Where a detailed IFRS implementation or accounting-policy assessment is required, that technical work should be separately reviewed rather than assuming a standard approach for every gold trader.
VAT is an important accounting consideration for UAE gold and precious-metals businesses.
The current UAE reverse charge mechanism covers qualifying transactions involving specified precious metals, precious stones and jewellery meeting the conditions set out in the applicable legislation.
The definition of precious metals for this mechanism includes gold, silver, palladium and platinum.
For a qualifying transaction between VAT-registered businesses, the recipient rather than the supplier may be responsible for accounting for VAT where the recipient intends to resell the goods or use them in producing or manufacturing qualifying goods and the other applicable conditions are satisfied.
This means the reverse charge mechanism should not simply be applied to every gold transaction.
The accounting records should retain the information and supporting documentation required to establish how the transaction was treated.
Our accounting support can include VAT-ready bookkeeping, transaction coding, reconciliations and working records. Formal VAT advice, registration, return filing or assessment of uncertain VAT positions should be scoped separately where required.
Reliable accounting records form the starting point for UAE Corporate Tax reporting.
For a gold trading business, this means purchases, sales, inventory, cost of sales, expenses, foreign-exchange movements and other relevant transactions need to be recorded consistently before the tax position can be assessed.
Our accounting work can support the preparation of Corporate Tax-ready financial records and schedules.
Corporate Tax registration, tax adjustments, advisory work and return filing remain separate tax services where specialist tax work is required.
Free-zone status does not automatically determine the Corporate Tax outcome of a gold trading company.
A company may need to assess whether it meets the conditions applicable to a Qualifying Free Zone Person and whether particular income qualifies for the relevant treatment under the UAE Corporate Tax regime.
The accounting records should therefore be capable of supporting the company’s activities, income and expenses without assuming that all free-zone income receives the same tax treatment.
Specialist Corporate Tax analysis should be performed separately where required.
Dubai Multi Commodities Centre is an important location for businesses operating in commodities and precious metals.
We support DMCC businesses with accounting records, management reporting, stock reconciliation and preparation of financial information required for year-end reporting.
Current DMCC requirements include the submission of audited financial statements and the relevant summary sheet within six months after the end of the company’s financial year.
Accounting preparation can help ensure that ledgers, stock records, reconciliations and supporting schedules are organised before they are provided to the appointed auditor.
The independent audit remains a separate engagement and must be performed by an appropriately appointed auditor in accordance with the applicable DMCC requirements.
Dealers in precious metals and stones are included within the UAE’s Designated Non-Financial Businesses and Professions framework where the applicable conditions are met.
This creates AML/CFT responsibilities that are separate from ordinary bookkeeping.
Accounting records can support the underlying transaction trail by maintaining organised information relating to purchases, sales, customers, suppliers, payments and inventory movements.
However, maintaining accounting records does not by itself satisfy the business’s wider AML/CFT obligations.
Customer due diligence, risk assessment, suspicious transaction reporting, goAML requirements, sanctions screening and other AML/CFT responsibilities should be managed within the appropriate compliance framework.
Where AML or goAML support forms part of a separate engagement, its scope and responsibilities should be defined clearly rather than being treated as an automatic part of bookkeeping.
Year-end preparation is easier when accounting and inventory records have been reconciled throughout the year.
Before an external audit, relevant accounting support may include preparing:
The objective is to provide organised financial information that the independent auditor can examine.
Accounting and audit-preparation support do not replace the auditor’s procedures, professional judgement or independent audit opinion.
We first review how the company operates, including its products, purchasing and sales process, stock system, transaction volume, currencies, bank accounts and existing accounting arrangements.
This establishes the scope before the accounting process is changed.
We assess the accounting file and available stock records to understand whether balances can be reconciled and whether historical issues need to be corrected.
This can include reviewing the chart of accounts, bank balances, customer and supplier ledgers and available inventory information.
Posting rules, reconciliation routines, reporting responsibilities and month-end processes are defined according to the agreed scope.
The aim is to create a process that can be followed consistently rather than correcting the same issues repeatedly at year-end.
Transactions are recorded and relevant bank, customer, supplier and inventory balances are reconciled according to the agreed reporting timetable.
Exceptions or unexplained differences can then be identified for follow-up.
Periodic financial reports and relevant VAT, Corporate Tax and year-end working information can be prepared from the reconciled accounting records.
Tax, AML/CFT and audit responsibilities outside the accounting scope remain separate professional engagements.
The exact deliverables depend on the agreed engagement.
A typical gold trading accounting scope may include:
Deliverables should be agreed in advance according to the size and complexity of the business rather than assuming that every gold trader requires the same accounting package.
Accounting for a gold trading business requires financial records that connect trading transactions with physical inventory and supporting documentation.
Our approach focuses on that connection.
Rather than treating the business as an ordinary retail or trading company, the accounting process can be structured around the company’s actual gold inventory, transaction flow, banking arrangements and reporting requirements.
Virtual Accountants LLC has an office in Dubai and supports businesses operating in Dubai and across the UAE.
We also keep service boundaries clear. Accounting support can prepare the records required for VAT, Corporate Tax, AML/CFT processes and external audit, but specialist tax advice, compliance responsibilities and independent audit work should be separately scoped where required.
If your gold, bullion, jewellery or precious-metals business needs stronger accounting records, stock reconciliation or financial reporting, we can review the existing setup and identify the accounting scope required.
Relevant factors include transaction volume, number of bank accounts, currencies used, inventory structure, condition of the existing books, reporting frequency and whether historical records need to be corrected.
Let our experts manage your books while you grow your business.
We’re always on the same page with Government Agencies, working together to get the job done!
Posted on Google
 kamil khan
Trustindex verifies that the original source of the review is Google.
My Experience of taking Accounting & Taxation services from Virtual Accountants (VA) was phenomenal. I would Reckon VA as best for Accounting & Tax services to SME'sPosted on Google Liubov ShchurkovaI’ve been working with Virtual Accountants for several years now, and they have consistently delivered the level of support and professionalism I expect. Their team is always highly responsive and prompt in communication, which makes the entire experience smooth and stress-free. What I particularly appreciate is their attention to detail — every question I’ve had has been answered thoroughly and clearly. All reports are prepared with precision and always delivered on time, without the need for reminders or follow-ups. Their reliability and expertise have made them a trusted partner in managing our company accounting needs. I can confidently recommend Virtual Accountants to anyone looking for accurate, timely, and dependable financial support.Posted on Google
 Thea DivinoWe appreciate your proactive communication and quick turnaround. It makes our job easier.Posted on Google
 Elin StensdotterWorking with Virtual Accountants continues to be a great experience. They are organised, reliable, and consistently proactive. Exactly what we need and look for in a financial partner. Their structured and forward-thinking approach allows us to stay focused on our core business, knowing they have everything else under control. It's incredibly reassuring to work with a team that not only keeps things in order but also anticipates our needs before we even raise them. We highly recommend Virtual Accountants to any company looking for a professional and dependable accounting partner.Posted on Google
 Info IskillWe’ve been working with this accounting company for over 3 years. Always professional, reliable, and a pleasure to deal with. They provide clear advice, work with integrity, and offer great value for money. Highly recommended!Posted on Google
 Kalle NeumannDear fellow company owners in UAE. I've been running my own company for 40 years, and I've had many accountants all over the world, but I can tell You that Umar Abdullah and his team at Virtual Accountants is one of the most dedicated and professional accountants I ever have experienced. Thank You Umar & Team!!!Posted on Google
 Farooq ButtMy accountant left and I was worried. Then I found Virtual Accountants and they made my life easy. Very happy with their team, highly recomended.Posted on Google
 Muhammad UmairVery good services, I am impressed by Mr. Sajid and his team.Posted on Google
 CA Sohel ShaikhI highly recommend Virtual Accountants LLC for their outstanding accounting and bookkeeping services in Dubai. Their team is highly professional, detail-oriented, and incredibly responsive. They have helped streamline our financial processes, ensuring accuracy and compliance with UAE regulations. What sets them apart is their dedication to client satisfaction—they provide timely reports, offer valuable financial insights, and are always available to address queries. Their expertise in VAT, payroll, and corporate tax has been invaluable to our business.Verified by TrustindexTrustindex verified badge is the Universal Symbol of Trust. Only the greatest companies can get the verified badge who has a review score above 4.5, based on customer reviews over the past 12 months. Read more
The scope can include bookkeeping, purchase and sales accounting, bank reconciliation, customer and supplier balances, gold inventory accounting, stock reconciliation, management reporting and year-end preparation.
VAT-ready and Corporate Tax-ready accounting records can also form part of the engagement.
The final scope depends on the company’s trading model and existing financial records.
The process compares the available inventory records with purchases, sales, transfers, adjustments and closing stock.
Where the company’s stock system records weight and purity, this information can be incorporated into the reconciliation so that physical or operational stock information can be compared with the accounting records.
Differences should be investigated and documented rather than automatically adjusted.
IAS 2 Inventories generally requires inventory to be measured at the lower of cost and net realisable value.
A separate measurement treatment applies to qualifying commodity broker-traders within the scope of the relevant IAS 2 provisions, where inventory is measured at fair value less costs to sell.
The correct treatment therefore depends on the facts and circumstances of the particular business.
No.
The reverse charge mechanism applies where the transaction and the parties meet the applicable conditions.
Under the current rules for qualifying precious metals, precious stones and jewellery, factors include the VAT registration status of the recipient and the recipient’s intention to resell the goods or use them in producing or manufacturing qualifying goods.
The facts and supporting documentation should be reviewed before applying the treatment.
The records should support the transaction, the parties involved and the basis on which the VAT treatment was applied.
Depending on the transaction, this can include invoices, declarations, VAT registration information and other supporting documentation required by the applicable rules.
Accounting records should remain consistent with those documents and the VAT working file.
Yes. Virtual Accountants supports businesses operating in DMCC.
The accounting scope can include bookkeeping, stock reconciliation, management reporting and preparation of year-end financial schedules.
Independent audit services and other work requiring an approved auditor remain separate.
Current DMCC guidance requires member companies to submit audited financial statements and the relevant summary sheet within six months after the end of each financial year.
The accounting records should therefore be prepared and reconciled in time for the company’s appointed auditor to carry out the independent audit.
No.
Being established in a free zone or DMCC does not by itself guarantee a 0% Corporate Tax rate.
The company needs to meet the applicable conditions for Qualifying Free Zone Person status, and the treatment of its income must be assessed under the UAE Corporate Tax rules.
Corporate Tax analysis and return filing should be separately reviewed where required.
Accounting support can help maintain organised transaction records and documentation that may be relevant to a gold trader’s AML/CFT processes.
However, bookkeeping does not replace customer due diligence, risk assessment, suspicious transaction reporting, sanctions screening, goAML responsibilities or other applicable compliance obligations.
Any separate AML/CFT or goAML support should have a clearly defined scope.
Yes. The accounting engagement can include reconciliations and financial schedules required to prepare the records for year-end audit.
This may include bank, customer, supplier and inventory reconciliations and supporting financial information.
The independent auditor remains responsible for the audit procedures and audit opinion.
The accounting approach can be adapted to the products and transaction structure of the business.
For bullion or jewellery traders, the records may need to incorporate different inventory categories, weights, purity information, purchases, sales and other stock movements.
The precise setup depends on the company’s inventory system and reporting requirements.
The appropriate frequency depends on the transaction volume, value of inventory, stock-control process and reporting needs of the business.
A high-volume gold trader may require more frequent reconciliation than a business with relatively limited stock movements.
The reconciliation schedule should be agreed as part of the accounting process rather than waiting until the year-end audit to identify differences.
Relevant information may include the company’s trade licence, existing accounting file, bank statements, sales and purchase records, customer and supplier balances, inventory reports and recent financial information.
For gold stock reconciliation, available weight, purity and movement records may also be required.
The initial review determines whether the existing records are suitable for ongoing accounting or whether historical cleanup is needed first.
Pricing depends on the actual accounting scope.
Important factors include transaction volume, number of bank accounts and currencies, inventory complexity, number of locations or stock records, reporting frequency, condition of the existing books and whether historical reconciliation is required.
A tailored quotation can be prepared after these requirements are reviewed.
Office 609, 6th Floor, Al Moosa Tower 1, Trade Centre 1, Sheikh Zayed Road, Dubai, UAE
Sharjah Media City (Shams), Al Messaned, Al Bataeh, Sharjah, United Arab Emirates.